
Bank statements, Tally and GST - made simple for CAs
Practical, no-fluff guides on converting bank statements to Tally, mastering voucher types, reconciliation, and keeping client statements on your own PC.
All articles
Allocating Work Without Letting the Tracker Lie
The moment a task list can say a return is done, it will say so about a return that is not. Keeping who-is-doing-what separate from what-is-actually-finished is the whole design.
Every Firm Now Deducts Tax on What It Pays Its Partners
From 1 April 2025 a firm deducts on remuneration and interest to a partner. The limit is small, and the words "credited to his account" make a year end journal entry enough to trigger it.
A 15G Is Not Just a Reason Not to Deduct
The declaration stops the deduction. What catches practices is the second half: it has to reach the quarterly return, with a number, or the processing treats it as a short deduction.
Turning a Narration Into a Party Name
POS 5177XXXX0927 SWIGGY BANGALORE is a party called Swiggy. Getting from one to the other reliably is a layered problem, and the tempting shortcuts both cost you something you need.
A Lender Statement Is Not a Bank Statement
It arrives looking like one, with two columns and a running balance. But it is written from the lender side of the account, and the balance on it is money the client owes.
Foreign Currency Lines on an Indian Statement
A spend abroad prints two amounts and a currency name, often on three separate rows. Only one of those figures is the entry, and the other two still matter.
A DSC Register That Survives an Expiry You Forgot
Every office loses a filing day to a certificate that lapsed quietly. The register that prevents it needs one field most registers leave out.
Reading a Notice: Which Department, Under What, and By When
Three facts turn a notice into a task with a date on it. Two of them are printed on the paper, and the third is the one practices most often get from memory.
A Settlement Report Is Not a Sales Report
The marketplace pays you a net figure built from a dozen deductions. Which column means what is the whole job, and a guessed column is how a fee gets booked as a sale.
A Bank Statement With No Year on Its Dates
Plenty of banks print "15 Mar" and leave the year to you. Working it out needs exactly two things, and neither of them is the year the file was opened.
A Credit Card Statement Is a Liability, Not a Bank Account
A charge credits the card and a payment debits it, which is the opposite of the habit a bank statement builds. The postings look the same on paper and the reasoning is not.
TCS on Sale of Goods Is Gone. Only the Buyer Deducts Now.
For five years a sale over Rs 50 lakh could attract tax from either side. From 1 April 2025 the seller collects nothing, and the Income-tax Act 2025 has no such collection at all.
The TDS Correction Statement: What Can Be Changed and What Cannot
A correction is not a re-filing. Some fields can be updated, some are carried forward untouched, some must be left empty, and a few cannot be changed at all. Knowing which is which is the whole job.
A Lower Deduction Certificate, and the Three Ways It Stops Working
A certificate under section 197 is not a blanket exemption for a payee. It is limited by dates, by the payment it names, and by an amount, and the amount is the limit practices forget.
Form 16 Part B: What Goes In It, and Where Each Figure Comes From
Part A and Part B of Form 16 are two different documents from two different places. Part B is built out of the fourth quarter return, which is why it cannot exist before that return is filed.
CA Practice Management Software: What It Should Hold and What It Should Leave to Tally
Most CA practice management software tries to replace the accounting package or ignores it. A practice needs the opposite: the office kept in one place, and the books left where the books already are.
Cheque Bounce Entry in Tally: Received, Issued and the Bank Charges
A returned cheque is two entries, not one: the reversal of the cheque, and the charge the bank levies for returning it. Here is each case, the voucher to pass, and what it does to the bank reconciliation.
The Rebate Is Section 156 Now, and It Still Misses Capital Gains
The 87A rebate has a new section number, the same two limits and the same blind spot: it never comes off tax charged at a special rate, which is where the client expected the relief.
A Broker Statement Is Not a Capital Gains Statement
Reading the file and working out the gain are two jobs, and most of the errors in capital gains come from a tool that did both at once without saying so.
Finding TDS the Client Missed, Under Two Different Acts
A payment nobody deducted on costs thirty per cent of the expense and interest on top. The books can tell you where to look, and the thing they cannot tell you is the one that decides the answer.
Every TDS Form Has a New Number From Tax Year 2026-27
24Q becomes 138, 26Q becomes 140, Form 16 becomes Form 130, and section 192 becomes section 392. The mapping, and which year each set still applies to.
ITR-U: Who Can File One, What It Costs, and the Form That Changes
Forty-eight months, four rates, three sets of bars, and a form that becomes a different form next year. The updated return, from the provisions rather than from a summary of them.
The Prefilled ITR JSON: What It Fills, and What It Must Not
The prefill is excellent for identity, bank accounts and tax credits, and it is not a source of income. Treating it as one is how a return ends up agreeing with the portal and disagreeing with the books.
Form 26AS and the AIS: Which One to Trust Before You File
They disagree more often than they agree, and the reasons are structural rather than suspicious. What each document is actually a record of, and which file to download.
Which ITR Form: The Tests That Rule ITR-1 and ITR-4 Out
The department publishes the rules that decide the form, and they fall into two very different groups: the ones that refuse the upload, and the ones that let it through and make the return defective.
GSTR-2B Against the Books: The Five Mismatches That Cost ITC
A 2B reconciliation does not produce one number. It produces four lists, and the credit you lose is almost always sitting in the two that look like clerical noise.
GSTR-1 JSON: Why the Portal Refuses a File That Looks Fine
The GSTR-1 upload JSON is validated against a published schema that refuses one unexpected key, a date that does not exist, and a place of supply the state list allows. Four things that get a clean-looking file rejected.
Cash Deposits, Section 269ST, and What the Tax Audit Asks
Two lakh received in cash from one person in one day attracts a penalty equal to the amount received. The bank statement shows the deposit, not the receipt behind it, and clause 31 of Form 3CD asks about the receipt.
Bank Interest Income and the TDS Credit That Comes With It
A bank credits interest net of tax, reports the gross figure to the department, and the difference is a credit the client is entitled to. Booking what the statement shows understates income and quietly forfeits the claim.
UPI Entries in Tally When the Statement Only Shows a Handle
A UPI line names a virtual payment address, a QR merchant code or an app, almost never the registered business. Four hundred such lines a month is where a bank import stops saving time and starts creating ledgers nobody recognises.
An Overdraft Is Not a Bank Balance: OD and CC Accounts in Tally
A cash credit account filed under Bank Accounts puts a borrowing in current assets. The balance sheet balances, every entry reconciles, and the working capital position it reports is wrong by twice the limit.
TDS on a Bank Statement: Why the Payment Is Short, and Where the Rest Went
A vendor invoiced ninety thousand and the bank shows eighty-one. The missing nine thousand is TDS, it has not disappeared, and booking the payment at the bank figure understates the expense and leaves the vendor permanently unreconciled.
The Contra Entries That Fail an Audit
A contra moves money between accounts the client already owns. Booked wrongly it inflates turnover, reverses cash flow, or records one movement twice, and every one of those survives a reconciliation.
When a Bank Statement Spans Two Financial Years
The Indian financial year ends on 31 March and almost no bank statement does. What that costs you, and how to import only the year you are actually working on.
Which Ledger Head Do Bank Charges Go Under in Tally?
Bank charges belong in Indirect Expenses, but that is the easy half. The harder half is that a bank statement mixes four different things under one label.
Bank Entries and the 44AB Tax Audit: What the Auditor Actually Looks At
The bank ledger feeds more clauses of Form 3CD than any other account in the books. Which clauses, what they are testing for, and where the evidence has to come from.
Ledger Scrutiny Before a Tax Audit: What to Check in the Bank Ledger
Reconciliation proves the balance is right. Scrutiny asks whether each entry is in the correct place, which is a different question and the one an auditor actually puts to you.
Undoing a Bad Tally Import (When 300 Vouchers Are Already In)
The import said it worked. Then you opened the ledgers. Tally has no undo for an import, so getting back out is a different job from getting in - and the deleting is not the hard part.
Handling Fifty Clients’ Statements in One Season
Processing one statement well and processing fifty are different problems. The second one is about sequencing and standardisation, and most firms solve it by working longer instead.
Multistock Invoices in Tally: The Cases That Break
A single invoice carrying several items at different tax rates is where most import tools quietly give up. The failure is usually in the rounding, and it is visible if you know where to look.
Opening Balance Mismatch in Tally: Finding the Break
A constant difference across every month is the most diagnosable error in accounting, because it tells you exactly where to look. The trick is recognising the pattern.
Input Tax Credit From Bank Entries: What Actually Qualifies
The bank statement carries more claimable GST than most firms take, and a few things that look claimable and are not. The difference is worth finding once per client.
Contra, Payment or Receipt? Picking the Right Voucher Every Time
Three voucher types cover almost every bank line, and choosing between them is not a style question. Pick wrong and the money looks like it came from somewhere it did not.
Getting Bank Statements Out of Clients Without Chasing Them
The document chase is treated as an unavoidable feature of practice. Most of it is caused by how the request is worded, and that part is fixable in an afternoon.
TallyPrime vs Tally ERP 9: What Actually Changes When You Import
The dangerous difference between Tally versions is not that older ones reject things. It is that they accept the voucher and silently drop the parts they do not understand.
What Manual Bank Entry Actually Costs Your Firm
Nobody bills for bank entry, so it reads as free. Work the real number out for one client and it is usually the most expensive unbilled thing the practice does.
Bank Reconciliation Statement Format in Tally (and What Each Line Means)
Tally builds the BRS for you once the bank dates are filled in. The format is not the hard part. Knowing which of the four buckets a difference genuinely belongs in is.
Tally Import Failed: What Each Error Actually Means
Tally import errors are mostly unhelpful, and the most dangerous case is not an error at all: an import that reports zero created while the vouchers are sitting in the company. Here is how to read what happened.
GST on Bank Charges: Booking It Correctly in Tally
Bank charges carry GST. Interest does not. Most bank statements show you one gross figure for both, and booking that figure straight to an expense ledger quietly throws away input credit every single month.
Why Every Imported Bank Entry Lands in Suspense (and How to Stop It)
Suspense is meant to hold the few entries you genuinely cannot classify. After a bulk import it often holds all of them. Here is the mechanical reason why, and what actually prevents it.
Is It Safe to Upload Client Bank Statements to Online Converters?
Free online statement converters are one search away and they work. The question is what you agreed to when you uploaded a client file, and who answers for it under the DPDP Act.
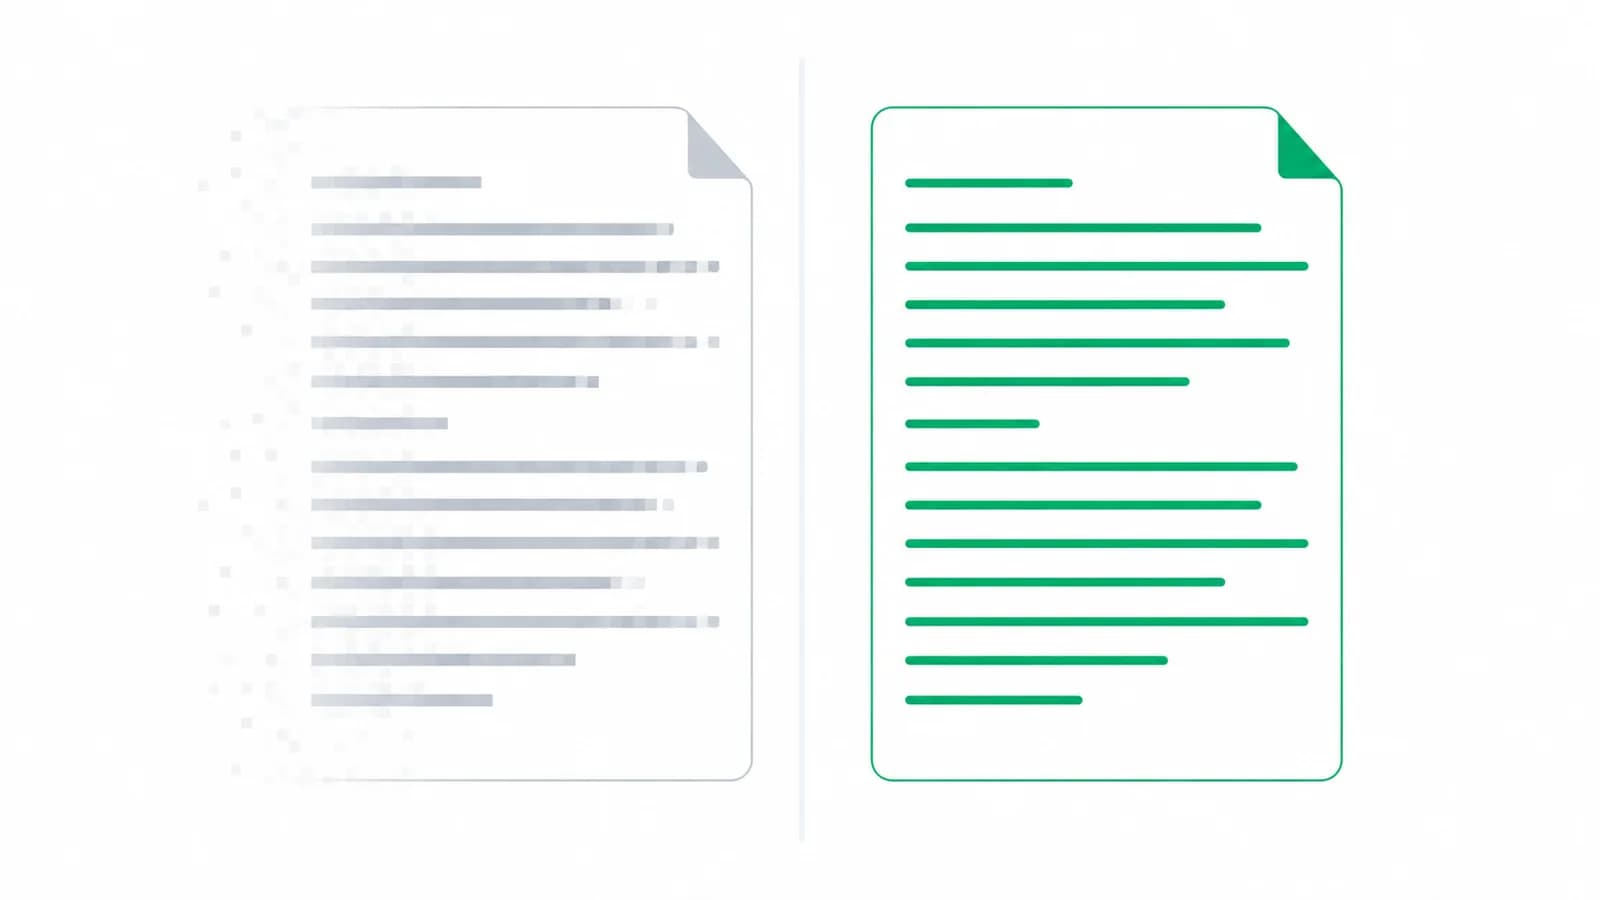
Scanned vs Text PDF Bank Statements: Why One Costs You Hours
The same statement can arrive in two forms that look identical on screen and differ by hours of work. Here is how to tell them apart in three seconds, and what to ask your client for instead.
How to Convert a Bank Statement to Tally Vouchers (The Fast, Accurate Way)
A practical, step-by-step guide for Indian CAs and accountants on turning any bank statement PDF into clean Tally vouchers - without manual data entry, and without uploading client data to the cloud.
Why Offline Bank Statement Processing Protects Your CA Firm (DPDP Act Explained)
India's DPDP Act changes the rules for how accountants handle client financial data. Here is why processing bank statements offline - on your own PC - is the simplest way to stay on the right side of the law.
The 7 Tally Voucher Types Every Accountant Should Master
Payment, Receipt, Contra, Sales, Purchase, Credit Note, Debit Note - a clear breakdown of when to use each Tally voucher type, with the sign conventions and GST gotchas that trip up even experienced users.
How to Reconcile a Bank Statement With Tally (And Why It Breaks)
Bank reconciliation should take minutes, not afternoons. Here is a clean method for matching your bank statement against Tally - plus the five reasons reconciliation usually fails and how to fix each.
Reclaim Your Busy Season: 6 Ways CAs Cut Bank-Entry Time by 90%
Busy season runs on hours you cannot get back. These six practical changes - from ledger conventions to automation on your own PC - help accounting firms cut bank data-entry time dramatically without sacrificing accuracy.